
Have you ever wondered how renting out your property affects your income tax and what benefits you can claim? Letting out a property can be a great way to earn a steady and passive source of income, but it also comes with specific tax implications. Understanding these tax regulations is essential—not only to ensure you comply with the law but also to help you make the most of available deductions and exemptions. Proper knowledge allows you to optimise your tax savings and avoid unnecessary penalties.
In this blog, we will take a closer look at what let-out property means, explain the step-by-step process of calculating income from such a property, and highlight the key tax benefits available to property owners under Indian tax laws. Let’s begin by understanding the basic concept of let-out property.
What is Let-Out Property?
When you rent or lease your property to someone else in exchange for rent, that property is known as a let-out property. This includes residential homes, commercial spaces, shops, or even vacant land leased under a formal agreement.
Key points about let-out property:
It generates rental income for the owner over a certain period.
Tenants get the right to use the property without owning it.
The rental agreement outlines the terms of use and payment.
If a property is left vacant or used personally, it may be considered a deemed let-out for tax purposes.
Let-out property status triggers specific tax rules on rental income, which we will discuss next. Understanding this classification is the first step in managing your property income effectively.
Now, let's move on to how to calculate the income from such a property.
Calculating Income from Let-Out Property
Calculating taxable income from a let-out property involves determining the Annual Value and then subtracting allowable deductions. To make this clearer, here’s a detailed explanation followed by an example.
What is Annual Value?
The Annual Value is essentially the rent that the property can earn in a year. It comprises two parts:
Gross Annual Value (GAV): The higher of actual rent received or the fair rent (market rent expected). If the property was vacant, the expected rent is still considered for taxation.
Net Annual Value (NAV): This is GAV minus municipal taxes paid by the owner.
Step-by-step calculation:
Determine Gross Annual Value (GAV): Actual rent received (what the tenant pays) or fair rent (market rental value decided by municipal authorities) — whichever is higher.
Deduct Municipal Taxes Paid: Subtract the property taxes paid by you to get the Net Annual Value (NAV).
Apply Standard Deduction: Deduct 30% of the NAV to cover maintenance and other expenses (allowed regardless of actual expenditure).
Deduct Interest on Home Loan: If you have a home loan on the property, deduct the interest paid during the year.
Calculate Taxable Income: NAV minus standard deduction and interest on home loan equals your taxable income from the property.
Example Calculation
Let’s consider Anita’s property:
Actual Rent Received: ₹1,15,000
Fair Rent: ₹1,36,000
Municipal Taxes Paid: ₹5,400
Step 1: Determine GAV
GAV = Higher of Actual Rent and Fair Rent = ₹1,36,000
Step 2: Calculate NAV
NAV = GAV – Municipal Taxes = ₹1,36,000 – ₹5,400 = ₹1,30,600
Step 3: Apply Standard Deduction (30% of NAV)
Standard Deduction = 30% of ₹1,30,600 = ₹39,180
Step 4: Deduct Interest on Home Loan
Assume Anita paid ₹40,000 interest on her home loan
Step 5: Calculate Taxable Income
Taxable Income = NAV – Standard Deduction – Interest Paid
= ₹1,30,600 – ₹39,180 – ₹40,000 = ₹51,420
So, Anita will pay tax on ₹51,420 as her income from the let-out property.
Calculating income from let-out property requires careful consideration of rents, taxes, and deductions. Using this stepwise approach and example helps simplify the process. Next, let’s explore the tax benefits you can claim to reduce your liability.
Tax Benefits on Let-Out Property
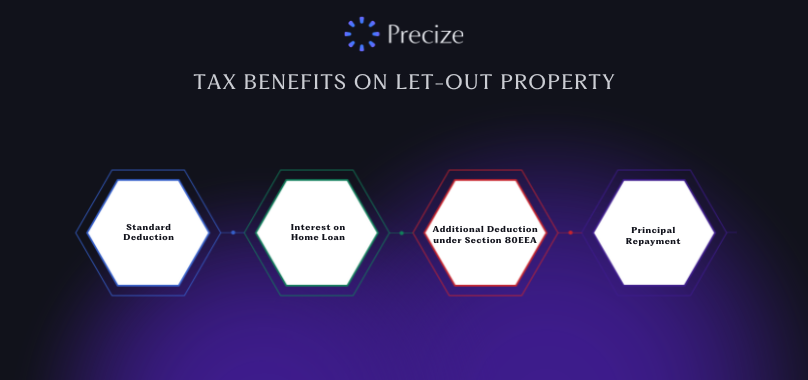
Owning a let-out property comes with several tax benefits designed to reduce your taxable income.
Main deductions available:
Standard Deduction: A flat 30% deduction on Net Annual Value for maintenance and repairs.
Interest on Home Loan: Deduct the entire interest paid on a loan taken for purchasing, constructing, or renovating the property, as permitted under Section 24.
Additional Deduction under Section 80EEA: Eligible taxpayers can claim up to ₹1.5 lakh extra deduction on home loan interest, over and above Section 24 benefits.
Principal Repayment (Old Regime Only): Up to ₹1.5 lakh deduction under Section 80C for principal repayments on home loans. This benefit is not available under the new tax regime.
These deductions make let-out properties an attractive investment by helping reduce your overall tax burden. Understanding and claiming these correctly is important for maximising benefits.
Let’s now look at how losses from let-out properties are treated for tax purposes.
Treatment of Losses from Let-Out Property
Sometimes, expenses like home loan interest exceed rental income, resulting in a loss. The tax treatment of this loss varies based on the tax regime you choose.
Under the Old Tax Regime:
You can set off loss from house property against income from other sources (like salary or business) up to ₹2 lakh per year.
Any unadjusted loss can be carried forward for 8 years, but can only be adjusted against income from house property in future years.
Under the New Tax Regime:
Losses from let-out property cannot be set off against other income heads.
Losses cannot be carried forward either.
Understanding loss set-off rules is essential to plan your tax strategy effectively based on the regime you follow.
Final Thoughts
Renting out property is a practical way to generate income and take advantage of several tax benefits available under Indian law. By understanding how to calculate your income, the deductions you can claim, and how losses are treated, you can manage your tax liability better and make informed investment decisions.
Use online calculators or government portals to simplify income calculation, and keep clear records of rent received, municipal taxes paid, and home loan interest for smooth tax filing.
Looking to optimise your property income and tax planning? Explore Precize today for expert financial solutions tailored to help you maximise returns and manage your investments efficiently.
Disclaimer
The information provided in this article is for general purposes only and should not be considered as professional financial or legal advice. Tax laws and regulations are subject to change and can vary depending on individual circumstances. You are advised to consult with a qualified tax professional or financial advisor to receive personalised guidance tailored to your specific situation before making any tax-related decisions.


